Price Point
Compare Polysil Irrigati with Similar Stocks
ScoreDashboard
Weak Long Term Fundamental Strength with a -3.50% CAGR growth in Net Sales over the last 5 years
- Low ability to service debt as the company has a high Debt to EBITDA ratio of 7.09 times
- The company has been able to generate a Return on Equity (avg) of 2.43% signifying low profitability per unit of shareholders funds
- PBT LESS OI(Q) At Rs 0.58 cr has Fallen at -65.1% (vs previous 4Q average)
- PAT(Q) At Rs 0.20 cr has Fallen at -89.7% (vs previous 4Q average)
With ROCE of 4.6, it has a Expensive valuation with a 2 Enterprise value to Capital Employed
Below par performance in long term as well as near term
Mojo ParametersStock DNA

Diversified consumer products

INR 143 Cr (Micro Cap)

486.00
33

0.00%

0.59

4.86%

2.61
Total ReturnsTotal Returns (Price + Dividend) 
Polysil Irrigati for the last several years.
Risk Adjusted Returns v/s
Returns Beta
 News & Corporate Actions
News
Polysil Irrigation Systems Ltd Locks at Lower Circuit With 4.93% Loss — Sellers Queue, No Buyers in Sight
At Rs 54.00, sellers were still queuing — but there were no buyers willing to take the other side. Polysil Irrigation Systems Ltd locked at its lower circuit of 5% on 24 Sep 2026, with unfilled sell orders and a frozen price.
Read full news article
Polysil Irrigation Systems Ltd Locks at Lower Circuit With 4.9% Loss — Sellers Queue, No Buyers in Sight
At Rs 56.80, sellers were still queuing — but there were no buyers willing to take the other side. Polysil Irrigation Systems Ltd locked at its lower circuit of 4.94% on 23 Sep 2026, with unfilled sell orders and a frozen price, reflecting persistent selling pressure in a micro-cap stock with limited liquidity.
Read full news article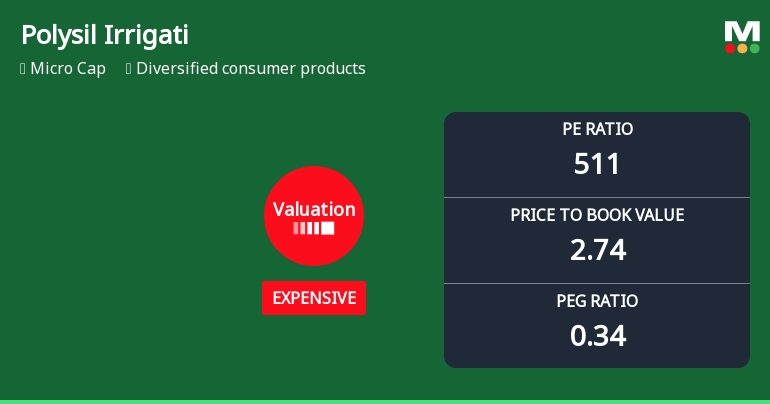
Polysil Irrigation Systems Ltd Valuation Shifts Signal Heightened Price Risk
Polysil Irrigation Systems Ltd, a micro-cap player in the diversified consumer products sector, has seen its valuation parameters shift notably, raising concerns about its price attractiveness. With a current price of ₹59.75, down 4.93% on the day, the stock’s price-to-earnings (P/E) ratio has soared to 510.86, moving from a very expensive to an expensive valuation grade. This article analyses the implications of these valuation changes in the context of historical trends, peer comparisons, and broader market performance.
Read full news article Announcements
Corporate Actions

No Upcoming Board Meetings

No Dividend history available

No Splits history available

No Bonus history available

No Rights history available
Key FactorsQuality key factors
Valuation key factors
Technicals key factors
 Technical Indicator Scale: Bearish, Mildly Bearish, Sideways, Mildly Bullish, Bullish Turned Shareholding
Shareholding Snapshot : Jun 2026
Shareholding Compare (%holding)
Non Institution
None
Held by 0 Schemes
Held by 0 FIIs
Bharat Kumar T Patel (21.27%)
Prakash Chhotalal Sheth . (10.87%)
43.51%
FinancialQuarterly Results Snapshot (Standalone) - Jun'26 - QoQ
 Compare with Peers

QoQ Growth in quarter ended Jun 2026 is -66.56% vs 1.53% in Mar 2026
QoQ Growth in quarter ended Jun 2026 is -93.20% vs 288.46% in Mar 2026

Half Yearly Results Snapshot (Standalone) - Mar'26
Growth in half year ended Mar 2026 is 96.55% vs 198.45% in Sep 2025
Growth in half year ended Mar 2026 is -3.50% vs 144.14% in Sep 2025
Nine Monthly Results Snapshot (Standalone) - Jun'26

YoY Growth in nine months ended Jun 2026 is 48.05% vs -10.67% in Jun 2026
YoY Growth in nine months ended Jun 2026 is 2.52% vs 13.57% in Jun 2026
Annual Results Snapshot (Standalone) - Mar'26
YoY Growth in year ended Mar 2026 is 228.15% vs -68.76% in Mar 2025
YoY Growth in year ended Mar 2026 is 251.89% vs -189.37% in Mar 2025
 Company CV
About Polysil Irrigation Systems Ltd

Company Coordinates